Strategic Tax Planning & Compliance
Guide (2026–2027)
As tax regulations continue to shift, staying ahead of compliance updates is vital for
optimizing wealth preservation and corporate cash flows. This guide outlines critical
corrections to obsolete tax rules and establishes the verified parameters required for the
current calendar year filing.
1. Urgent Corrections to Legacy Guidelines
Several common assumptions based on previous tax frameworks are now legally incorrect
or significantly outdated.
Please audit your active strategies against the following critical updates:
Home Equity Interest Limitations: Contrary to historical rules, interest on home equity
loans or lines of credit (HELOCs) is completely non-deductible unless the proceeds
are exclusively used to buy, build, or substantially improve the specific home securing
the loan. Tracking and tracing the exact deployment of these funds is mandatory.
Required Minimum Distribution (RMD) Realignment: The statutory age for
commencing RMDs from traditional IRAs and 401(k) plans has escalated to Age 73.
Failure to execute required distributions triggers an immediate 25% excise tax on the
shortfall.
Bonus Depreciation Phase-Down: The era of 100% first-year bonus depreciation has
transitioned. For qualified assets placed in service, the deduction limit has
systematically reduced to 20%, moving toward complete sunset.
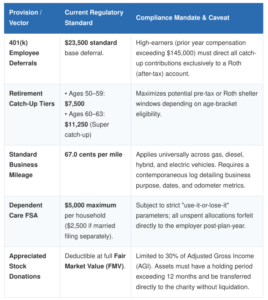
2. Key Statutory Limits and Frameworks
Ensure your payroll, accounting, and personal retirement structures conform strictly to the
active regulatory benchmarks:
3. 529 College Savings Structural Advantages
The 529 structure remains an exceptionally resilient vehicle for multi-generational
education funding, offering robust tax advantages:
-Tax-Deferred Growth: Portfolio rebalancing and earnings accrue completely sheltered
from annual federal and state capital gains liabilities.
-Tax-Free Qualified Distributions: Withdrawals remain entirely tax-free when deployed
for tuition, mandatory fees, books, equipment, and up to $10,000 annually for K-12
tuition or qualified student loan amortization.
-State-Level Incentives: Depending on state residency, contributions may yield
immediate state income tax deductions or tax credits.
Strategic Advisory Note: Stockholders in closely-held corporations evaluating
whether to distribute corporate profits via dividends or year-end bonuses must
conduct a unified corporate-and-individual tax drag analysis. While qualified
dividends leverage preferential long-term capital gains rates, they remain subject to
double taxation at the entity level, whereas bonuses are deductible to the corporation
but face full ordinary income and FICA rates.
Compliance Notice: This document is prepared for informational and educational purposes only. It
does not constitute formal legal, accounting, or strategic tax advice. Because individual and
corporate tax positions vary based on jurisdiction, corporate structure, and aggregate income, you
must consult your Budwitz & Meyerjack professional to finalize any structural adjustments to your
tax workflow. AI-generated text may include inaccuracies.

